



How do EU allowances differ from other carbon assets in Europe?




EU allowances differ from other carbon assets in Europe because they are regulatory compliance units, not certificates of emissions reductions. An EU allowance, or EUA, gives its holder the right to emit one tonne of carbon dioxide equivalent under the EU Emissions Trading System (EU ETS). A voluntary carbon credit instead represents a claimed reduction, avoidance or removal of emissions under a particular crediting framework.
That distinction determines what each asset can do. A company covered by the EU ETS cannot replace its allowance surrender obligation with voluntary offsets or carbon removal credits. Equally, buying EU allowances does not, by itself, demonstrate that a company has reduced its own emissions or removed carbon from the atmosphere. The shared “one tonne” denomination does not make these assets interchangeable.
An allowance represents permission under a cap, not a project outcome
The EU ETS places a declining cap on emissions from covered activities, including electricity and heat generation, specified industrial processes, aviation within its applicable scope, and maritime transport. Regulated operators monitor and report emissions, obtain independent verification and surrender eligible allowances against their obligations.
Allowances enter circulation principally through auctions and free allocation under the system’s rules. They are held and transferred through the Union Registry. Free allocation changes how an operator receives allowances; it does not remove the requirement to account for emissions and surrender the required units.
An EUA therefore does not need an underlying wind farm, forestry project or carbon capture installation. Its validity comes from the regulatory system that creates it. The environmental mechanism operates through the emissions cap and compliance requirements, rather than through a separate assertion that each allowance represents an additional tonne saved.
Project-based credits follow a different logic. A project must quantify an outcome against a baseline or other approved accounting approach. Its credibility depends on whether that outcome was measured correctly, whether it would have happened without the crediting incentive, and whether emissions were displaced elsewhere or stored carbon could later be released.
The main differences at a glance
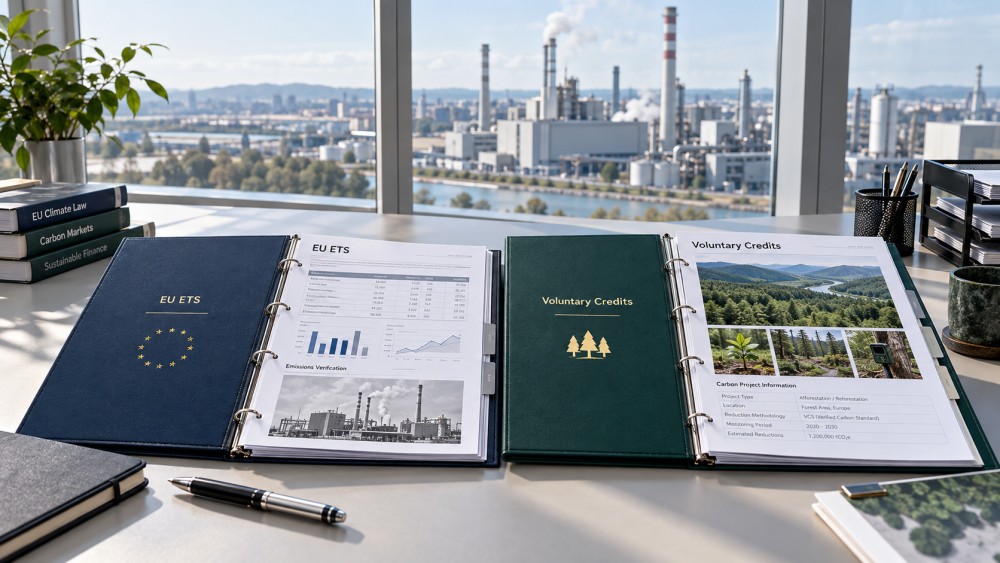
“Carbon asset” is a broad market label, not a single legal category. It can describe allowances, credits and financial instruments referencing them. Comparing prices without identifying the underlying unit can therefore produce misleading conclusions.
Voluntary credits face questions that EU allowances do not
A voluntary credit generally represents one tonne of CO₂ equivalent reduced, avoided or removed. Its issuance follows a programme’s methodology, monitoring requirements and validation or verification procedures. Those requirements differ between programmes and project types.
For an avoided-deforestation credit, the central question includes how much forest loss would otherwise have occurred. For an emissions-reduction project, it includes whether regulation or commercial conditions would have delivered the same reduction without credit revenue. These are baseline and additionality questions. An independent verifier can assess compliance with a methodology, but verification does not eliminate uncertainty in the methodology’s assumptions.
EUAs do not carry these project-level uncertainties. One valid EUA is not assigned a premium because it came from a particular auction or was previously held by a particular factory. Within the applicable trading rules, allowances are standardised compliance units. Credits can differ substantially by methodology, project location, issuance year, delivery status and associated benefits.
Voluntary credits also cannot be treated as a lower-cost substitute for EUAs. International project credits had a limited role in earlier EU ETS periods, but they are not accepted for EU ETS compliance in the phase beginning in 2021. Historical references to offset eligibility should not be applied to current surrender obligations.
Carbon removal credits are distinct from avoided emissions
Removal credits concern CO₂ taken out of the atmosphere and stored. Examples include biological storage through vegetation and soils, and technological pathways such as direct air capture with geological storage. Avoiding an emission that would otherwise have occurred is not the same physical outcome.
Even within removals, a tonne is not fully described by its quantity. Forest carbon can be released through fire, disease or land-use change. Geological storage has a different risk profile and monitoring framework. Assessment must also consider energy use and other project emissions, because gross CO₂ captured is not necessarily equal to net CO₂ removed.
The EU’s Carbon Removals and Carbon Farming Certification Regulation, Regulation (EU) 2024/3012, establishes a voluntary framework covering permanent carbon removals, carbon farming and carbon storage in products. It is not a mechanism that automatically converts certified outcomes into EU allowances.
Certification, credit issuance and compliance eligibility are separate questions. A removal can meet a certification framework without becoming eligible for surrender under the EU ETS. Claims about “EU-certified carbon” therefore require clarification about the certification category, methodology, storage duration and permitted use.
European location does not create a single compliance market
An asset issued or traded in Europe is not necessarily an EU ETS asset. The UK ETS has its own allowances, known as UKAs, with separate supply rules and prices. Swiss allowances belong to another system, although the Swiss and EU emissions trading systems are formally linked. Acceptance depends on the relevant legal arrangements, not geographical proximity.
The same distinction matters for the Carbon Border Adjustment Mechanism. CBAM certificates are instruments for meeting obligations connected with embedded emissions in covered imports. Their pricing references EU ETS auction prices, but they are not freely tradable EUAs. A relationship to the EUA price does not make a certificate the same asset.
Renewable electricity guarantees of origin are different again: they document specified attributes of electricity generation rather than providing permission to emit or independently establishing a one-tonne carbon offset.
Price reflects different obligations and different risks
EUA prices reflect the interaction of regulatory supply and demand for compliance, alongside trading activity and expectations. Relevant variables include the cap, auction volumes, the Market Stability Reserve, industrial production, electricity generation and fuel-switching economics. The carbon price influences operating decisions, while changes in those decisions affect allowance demand.
Credit prices reflect a different set of variables: project costs, perceived environmental integrity, methodology, delivery timing, storage durability and buyer preferences. A low-priced avoidance credit and a high-priced durable removal may share a unit denomination while representing fundamentally different outcomes.
Market quotations also need careful reading. A spot EUA transaction concerns an allowance, whereas an EUA futures contract provides exposure to delivery at a specified future date under the contract’s terms. A carbon fund or exchange-traded product adds its own structure, fees and tracking characteristics. None should be assumed to be identical to holding allowances in a registry account.
Surrender, retirement and emissions claims are separate actions
Surrendering EUAs fulfils a regulated emissions obligation. Retiring voluntary credits generally takes them out of circulation for a stated purpose. Cancelling allowances is another action, but its environmental effect must be assessed within the EU ETS’s supply rules, including the Market Stability Reserve; it should not automatically be described as a measured one-tonne atmospheric reduction.
These distinctions also constrain corporate claims. Buying EUAs does not establish carbon neutrality, and retiring credits does not erase reported operational emissions. Credible reporting keeps the emissions inventory, internal reductions, compliance instruments and external climate contributions identifiable.
The decisive comparison is therefore not simply “which carbon asset costs less?” It is “what obligation or environmental outcome does this unit address?” EUAs address emissions compliance within a capped system. Credits document outcomes under crediting methodologies. Removal credits add specific questions about atmospheric extraction and storage. Their value can only be interpreted correctly once those functions are kept separate.
- Last One:No more articles
- Next Article:Can a digital supplier discovery platform verify overseas suppliers?Oct 25, 2026
Related News
- 00
0000-00
How do EU allowances differ from other carbon assets in Europe? - 00
0000-00
Can a digital supplier discovery platform verify overseas suppliers? - 00
0000-00
Which drilling systems are suited to long-lateral shale wells? - 00
0000-00
Which sectors are driving demand in the chemical engineering market? - 00
0000-00
How to assess lifecycle emissions from CCUS for low-carbon cement
Related tags
Weekly Insights
Stay ahead with our curated technology reports delivered every Monday.